

Nidal Chikho to Steel Network: China Is Not Competing on Price Alone — It Has Built an Industrial System That Is Hard to Match
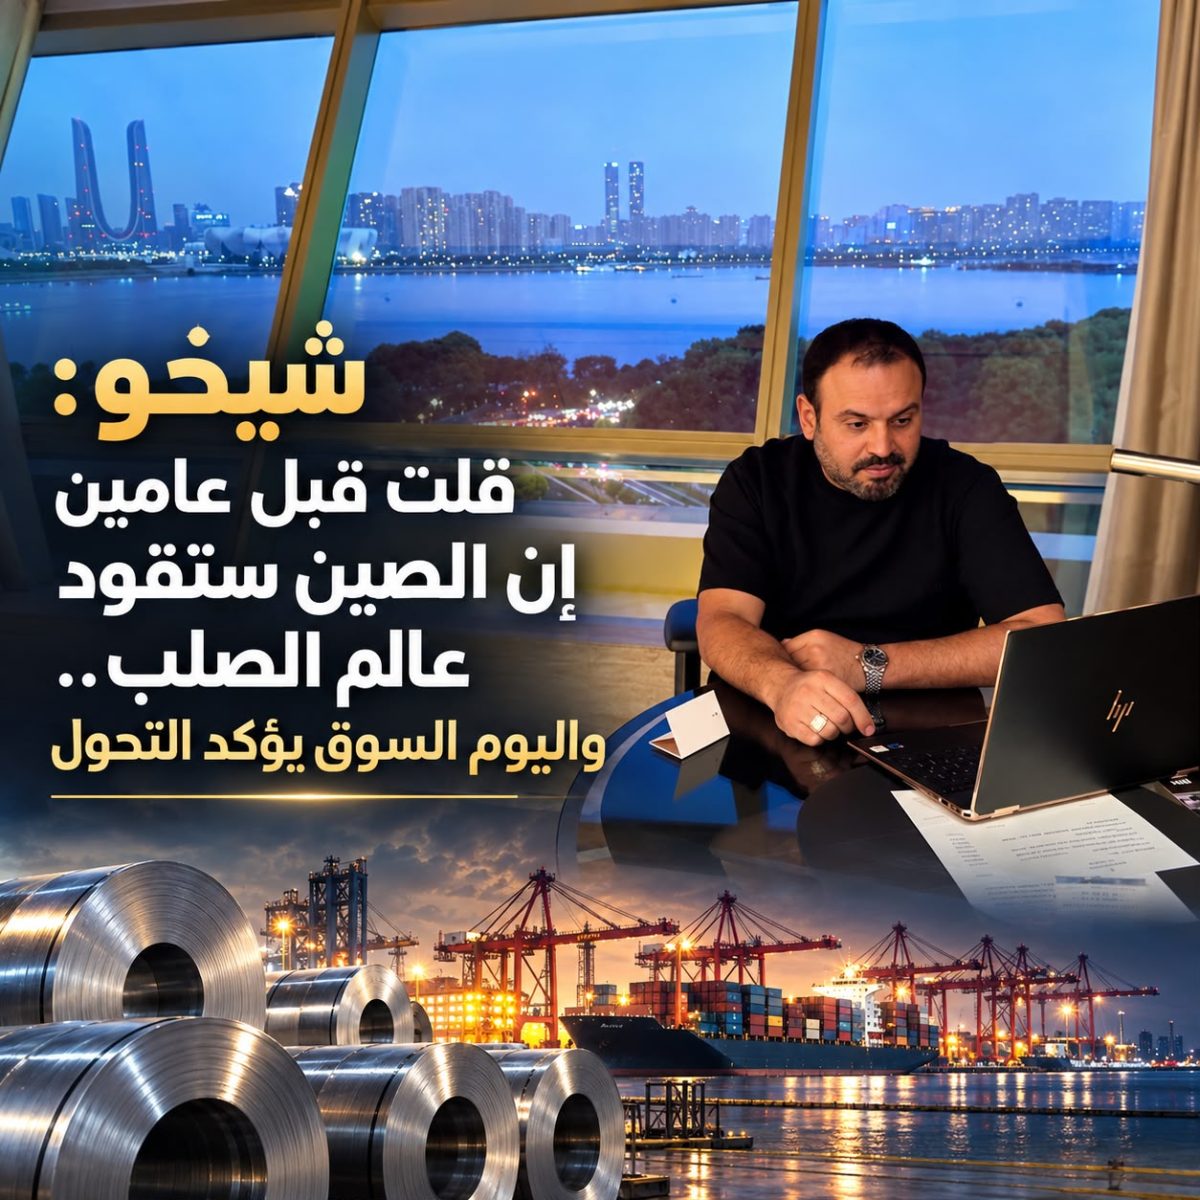

Industrialist and businessman Nidal Chikho, Chairman of CHIKHO GROUP, told Steel Network in an exclusive interview that developments in the steel market during 2026 have reinforced a view he first expressed nearly two years ago: China is increasingly positioning itself as the most influential force in the global steel industry and trade.
Chikho bases his assessment on his frequent visits to China, direct dealings with Chinese steelmakers, and close monitoring of steel prices and international trade.
Steel Network: Nearly two years ago, you said China would lead the steel world. Do you still hold that view?
Nidal Chikho:
“More than ever. When I said China would lead the steel world, I was not talking about price alone. I was talking about an integrated industrial system — production scale, speed, flexibility, supply chains and the ability to make decisions quickly. Today, I am even more convinced of that view.”
Steel Network: Chinese competition has long been associated with low prices. What has changed from your perspective?
Chikho:
“Anyone who deals directly with Chinese mills knows that it is no longer just about price. There has been remarkable development across hot-rolled, cold-rolled, galvanized and color-coated steel production, both in operational efficiency and quality, as well as in response times.”
Recalling an incident he witnessed during a visit to a color-coated steel plant in China, Chikho said:
“One of the machines broke down during production. Within roughly half an hour, the faulty component had been removed and sent for repair, and about two hours later the production line was running again. That incident says a lot about the Chinese industrial mindset: time is part of the cost of production.”
According to Chikho, the same speed is increasingly evident in customer service, commercial negotiations, supply-chain management and decision-making.
Steel Network: How have the steel prices you monitor moved since the beginning of 2026?
Chikho:
“For galvanized and color-coated steel, we have seen increases of around $35–55 per tonne from the beginning of the year through September 20. But it is important not to attribute the entire increase to steel prices. A significant part came from higher freight, transportation and logistics costs.”
For hot-rolled coil (HRC), Chikho estimates that the increase on an FOB basis has been more limited, at approximately $25 per tonne over the same period.
He added:
“Despite wars and disruptions in energy and shipping, we have not seen an explosion in steel prices. The reason, in my view, is clear: enormous production capacity and intense global competition.”
This view is consistent with broader structural pressures in the global steel industry. The OECD estimated global excess steelmaking capacity at around 640 million tonnes in 2025, with the figure potentially reaching approximately 745 million tonnes by 2028 if announced capacity expansions proceed. China’s steel exports also reached a record level of around 131 million tonnes in 2025.
Steel Network: What do you expect from the market during the final quarter of 2026?
Chikho:
“I expect October to be relatively better, supported by industrial activity and infrastructure projects in China. However, as we move into November and December, seasonal pressure could return, particularly for steel products linked to the construction sector.”
Rather than the beginning of a major price rally, Chikho expects the market to remain within relatively limited ranges, with some upward momentum possible during October.
Based on his reading of current indicators, Chikho expects rebar prices during the fourth quarter to trade within an equivalent range of approximately $435–485 per tonne in the Chinese market, while HRC could prove more resilient, at around $465–500 per tonne.*
He explained:
“I do not currently see a technical basis for sharp and sustained price increases. A strong rally would require a meaningful reduction in production alongside a genuine improvement in demand. If demand remains weak while excess supply persists, the upside will remain limited.”
The cautious outlook is also broadly consistent with the World Steel Association’s April 2026 forecast, which projected global steel demand growth of just 0.3% in 2026, while Chinese steel demand was expected to decline by around 1.5%.
Steel Network: If a steel trader or investor wants to understand where the market is heading, which indicators should they watch?
Chikho:
“Today, watching the price per tonne is not enough. Watch China — production, inventories, iron ore, coal and coke, futures, exports and mill decisions. These are the indicators that will determine the direction of the market.”
Concluding his interview with Steel Network, Chikho said:
“Two years ago, I said China would lead the steel world. Today I say: the market waits for no one — and China understood the value of time early.”
Nidal Chikho
Chairman
CHIKHO GROUP